Planning for Parenthood: How Working Moms Can Make Life Insurance Part of the Family Plan
Preparing for a baby changes the way you think about money, time and the future. For a working mom, the list can feel endless: medical appointments, childcare, household expenses, parental leave, career plans and the small everyday purchases that quickly add up. Amid all of this, life insurance may not feel urgent—but it can be an important part of protecting the people who depend on you.
Life insurance is not about expecting the worst. It is about creating a financial safety net so that, if you were no longer there to provide income or care, your family would have more options and fewer immediate financial pressures. The right approach starts with your family’s needs, not with a sales pitch or a one-size-fits-all number.
Why Life Insurance Matters for Working Mothers
A mother’s contribution to a family is much bigger than her monthly salary. Her income may pay for rent or a home loan, groceries, childcare, school fees, healthcare and savings. She may also provide unpaid care, organise appointments, manage routines and support a partner or older relatives. If that support disappeared, the family could face both a loss of income and new costs for care.
Life insurance can provide a financial benefit to the named beneficiary when the insured person dies, subject to the policy’s terms and conditions. That money may help cover essential living costs, outstanding debts, childcare or education expenses. It cannot replace a parent, but it may give loved ones time and financial flexibility during an extremely difficult period.
Start With Your Family’s Real Financial Picture
Before comparing policies, take a quiet hour to map your household finances. Include both the expenses you pay directly and the work you contribute at home. If you share finances with a partner, make the plan together so that neither person’s contribution is overlooked.
- Monthly essentials: Housing, utilities, food, transport, childcare, healthcare and other regular bills.
- Existing debts: Home loans, education loans, personal loans and other obligations that could remain for your family.
- Future goals: Schooling, higher education, a home purchase or other long-term priorities.
- Available resources: Savings, investments, existing life cover, employer-provided benefits and your partner’s income.
- Caregiving needs: The potential cost of childcare, household help or other support if your time and care were no longer available.
This simple review helps you see what your family might need—and what resources are already in place. Keep the estimates realistic and revisit them when your circumstances change.
How Much Life Insurance Cover Might You Need?
There is no single amount that suits every working mom. A useful starting point is to estimate the money your family would need over time, then subtract the resources that could reasonably be used for those needs. Consider income replacement, debts, childcare and education goals, final expenses, and a buffer for unexpected costs.
For example, a family with a large home loan and a young child may have different needs from a family with lower debt, substantial savings and older children. Your salary matters, but it is not the only measure of your financial value to the household. Include the cost of replacing unpaid caregiving as well.
Online calculators can help organise your thinking, but their results are estimates rather than personalised financial advice. Review the assumptions carefully and consider speaking with a qualified, appropriately licensed insurance or financial professional before deciding on cover.
Understand the Main Types of Life Insurance
Term life insurance
Term insurance generally provides life cover for a selected period. If the insured person dies while the policy is in force, the benefit is paid according to the contract. It is often considered by families seeking a defined amount of protection during years when children are young, a mortgage is outstanding or income replacement is especially important. Check the exact policy term, premium schedule, exclusions and conditions before buying.
Life insurance with savings or investment features
Some policies combine life cover with savings or investment-related benefits. Their costs, guarantees, risk levels, surrender rules and potential returns can differ substantially. Do not assume that a policy with a savings element is automatically better—or that projected returns are guaranteed. Separate the protection need from other financial goals and compare the full terms.
Employer-provided life cover
Your employer may provide group life insurance as part of workplace benefits. It is worth checking the amount, eligibility rules and what happens if you change jobs or take an extended break. Employer cover can be useful, but it may not be enough for your family’s needs and may not continue after employment ends. Read the benefit documents rather than relying on assumptions.
Questions to Ask Before Choosing a Policy
When comparing life insurance policies, look beyond the headline premium. The cheapest option is not necessarily the best fit if the coverage period, benefit amount or conditions do not match your goals.
- What events are covered, and what exclusions or limitations apply?
- How long does the policy provide cover, and when does protection begin?
- Are premiums fixed or can they change? What happens if a payment is missed?
- What documents and disclosures are required when applying?
- What are the rules for nomination or beneficiaries, and how can these details be updated?
- Are optional riders available, what do they cost, and what conditions apply?
- What is the process for making a claim, and which documents may be required?
- Is the insurer authorised by the relevant regulator in your country?
Read the policy document and benefit illustration carefully, including the fine print. Give accurate answers to questions about health, occupation, smoking and other information requested in the application. Incomplete or inaccurate disclosures can create problems when a claim is assessed.
Planning Around Pregnancy, Parental Leave and a Career
Parenthood can change your income for a while, even when you plan to return to work. Before leave begins, review your budget and understand how salary, bonuses, employer benefits and insurance coverage may change. If you are considering buying a policy, ask the insurer how its application process handles pregnancy and any medical information it requires; underwriting rules vary by insurer and product.
Do not assume that pregnancy automatically makes you ineligible, or that every application will be treated the same way. Answer all application questions honestly and ask for written clarification if something is unclear. If you already have a policy, review its terms and keep premiums up to date rather than cancelling cover without understanding the consequences.
It can also help to keep a shared household folder with policy documents, premium due dates, insurer contact details and instructions for your partner or trusted family member. A plan is more useful when the people who may need it know where to find it.
Do Not Forget the Non-Financial Side of Family Protection
Life insurance is only one piece of a broader family plan. Depending on your circumstances and local laws, you may also want to review health insurance, emergency savings, parental leave benefits, a will, guardianship wishes for a child, and instructions for accessing important accounts. These are separate arrangements, so do not assume a life insurance nomination automatically handles every inheritance or guardianship question.
If your child is a minor, ask the insurer and a qualified legal professional how benefits would be handled and whether any additional arrangements are appropriate. Rules differ by jurisdiction and policy, so avoid relying on generic advice for a decision with legal consequences.
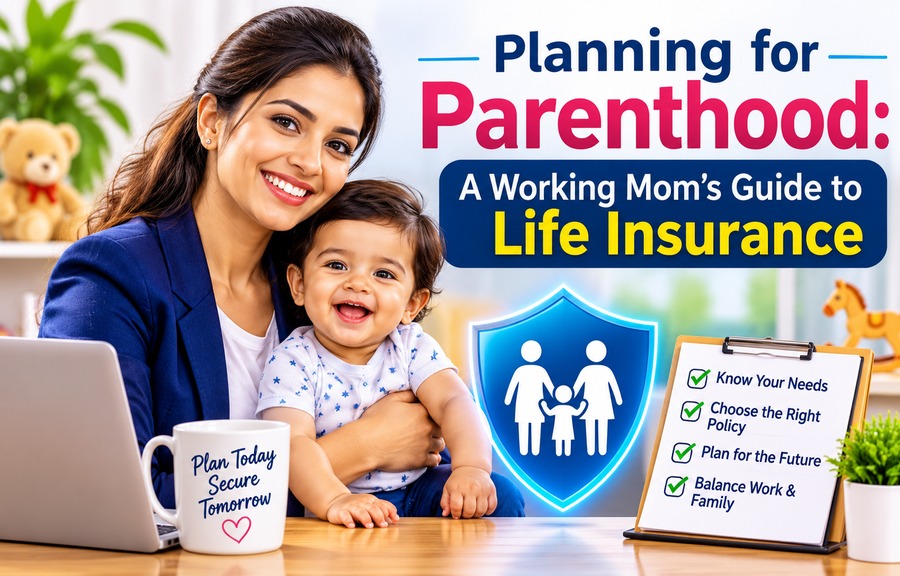
A Simple Life Insurance Checklist for New Parents
- Estimate household expenses, debts and future child-related costs.
- List existing individual and employer-provided life cover.
- Decide how much income replacement and caregiving support your family may need.
- Compare policy terms, exclusions, premiums and insurer credentials.
- Complete applications accurately and keep copies of all submitted information.
- Review the issued policy and check the name, cover amount, term and premium details.
- Confirm nominee or beneficiary information and understand how to update it.
- Store documents securely and tell a trusted person where they can be found.
- Set a reminder to review the plan after a birth, home purchase, job change or major financial change.
Common Mistakes to Avoid
Waiting until everything feels settled
Family life rarely becomes perfectly predictable. Start by gathering information and understanding your options; you can make a more informed decision once you know your needs and the policy terms.
Insuring only the higher earner
If a mother contributes income or substantial unpaid care, her absence can create a financial gap too. Consider each adult’s contribution rather than assuming only one person needs cover.
Choosing a number without doing the maths
A round figure may be convenient, but it can overlook debt, childcare or long-term goals. Use a written estimate and update it as your family grows.
Forgetting to review the policy
A policy that suited you before parenthood may need to be reviewed after a new child, a change in income or a major loan. Review does not always mean buying more insurance; it means checking that your current arrangements still fit.
Frequently Asked Questions
Should a working mom consider life insurance before having a baby?
It can be sensible to review your financial protection while planning a family. The best timing and policy depend on your circumstances, eligibility and the insurer’s terms. Compare options carefully and provide accurate information in any application.
Does a stay-at-home parent need life insurance too?
Potentially, yes. Replacing childcare, household management and other unpaid care can be expensive. A family should consider the financial effect of losing either parent’s contribution, not just salary.
Is employer-provided life insurance enough?
It depends on the benefit amount, your family’s needs and the conditions attached to the cover. Check whether it continues if you leave your job or take a career break, and compare it with your estimated protection needs.
What should I do with my policy after my baby is born?
Review your cover amount, policy term, nominee or beneficiary details and any related family arrangements. Keep the insurer informed of changes when required by the contract and applicable rules.
Can I choose my child as a nominee or beneficiary?
Rules and procedures vary by country and insurer, particularly when a nominee is a minor. Ask the insurer how the benefit would be received and consider qualified legal guidance before making arrangements.
Is this article personal financial advice?
No. This guide is for general educational purposes. Insurance products, regulations, taxes and legal arrangements vary by location. Read the relevant policy documents and consult an appropriately qualified professional for advice tailored to your situation.
Reliable Resources for Further Reading
- Insurance Regulatory and Development Authority of India (IRDAI) — official regulator information and policyholder resources for India.
- LIC: Know Your Life Insurance — a general introduction to life insurance concepts.
- LIC: Policy Conditions — information about policy documents, nomination and premium payments.
Final Thoughts: Protection Is Part of Planning for the Future
Working motherhood often means carrying several responsibilities at once. Planning for life insurance does not need to become another source of pressure. Begin with a clear picture of your household finances, understand the role you play through both paid work and care, and compare policies based on their actual terms—not fear or marketing promises.
A thoughtful family protection plan can offer greater clarity during a major life transition. Review it as your family grows, keep important documents accessible to trusted people, and make decisions that fit your budget and priorities. The goal is not to plan for every possible outcome; it is to give the people you love a stronger financial foundation.